Systema Monitor (Week 45)
Week ending 6 November: the Nifty 500's best week in our records, back above its long-term trend. But momentum stocks slipped back into Drawdown.
Market data in this review is as of 6 November 2026.
 Watch the video: Systema Monitor (Week 45)
This is market commentary for information only. It’s not investment advice.
Hello, and welcome to Systema Monitor for the week ending the sixth of November.
Market Regime
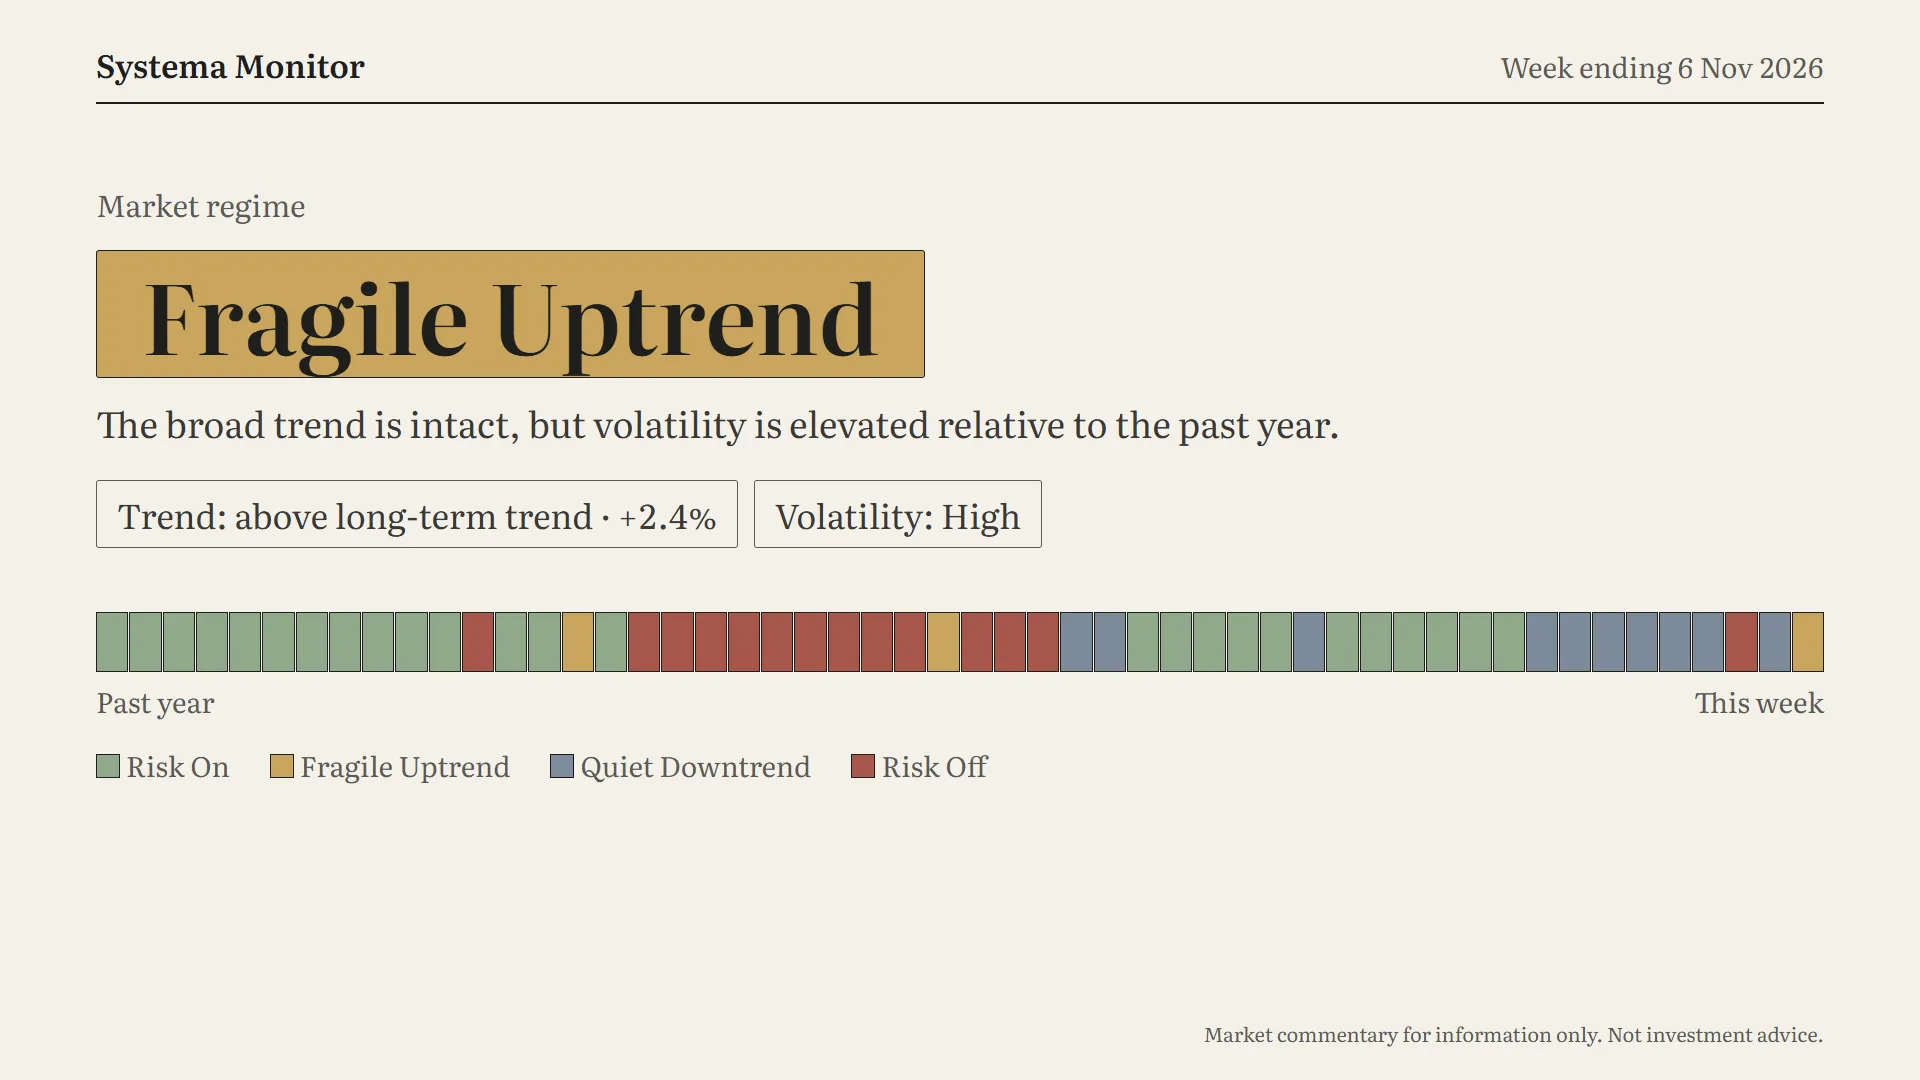
Two weeks ago the regime was Risk Off. Last week it eased back to Quiet Downtrend. This week it moved up again, to Fragile Uptrend: the broad trend is intact, but volatility is elevated relative to the past year.
The two readings moved in opposite directions. Trend: the broad market rose from about 4.4% below its long-term trend to about 2.4% above it. That’s the first time it has been above the trend since the week ending 4 September. Volatility, though, rose from Caution to High. A market can be volatile on the way up as well as on the way down, and a 7% week is a big move whichever way it goes.
That combination explains the label. The trend has turned up, but the market is still swinging hard, so the uptrend is fragile. The past-year strip now ends with one ochre block, the first Fragile Uptrend week since May.
Scoreboard
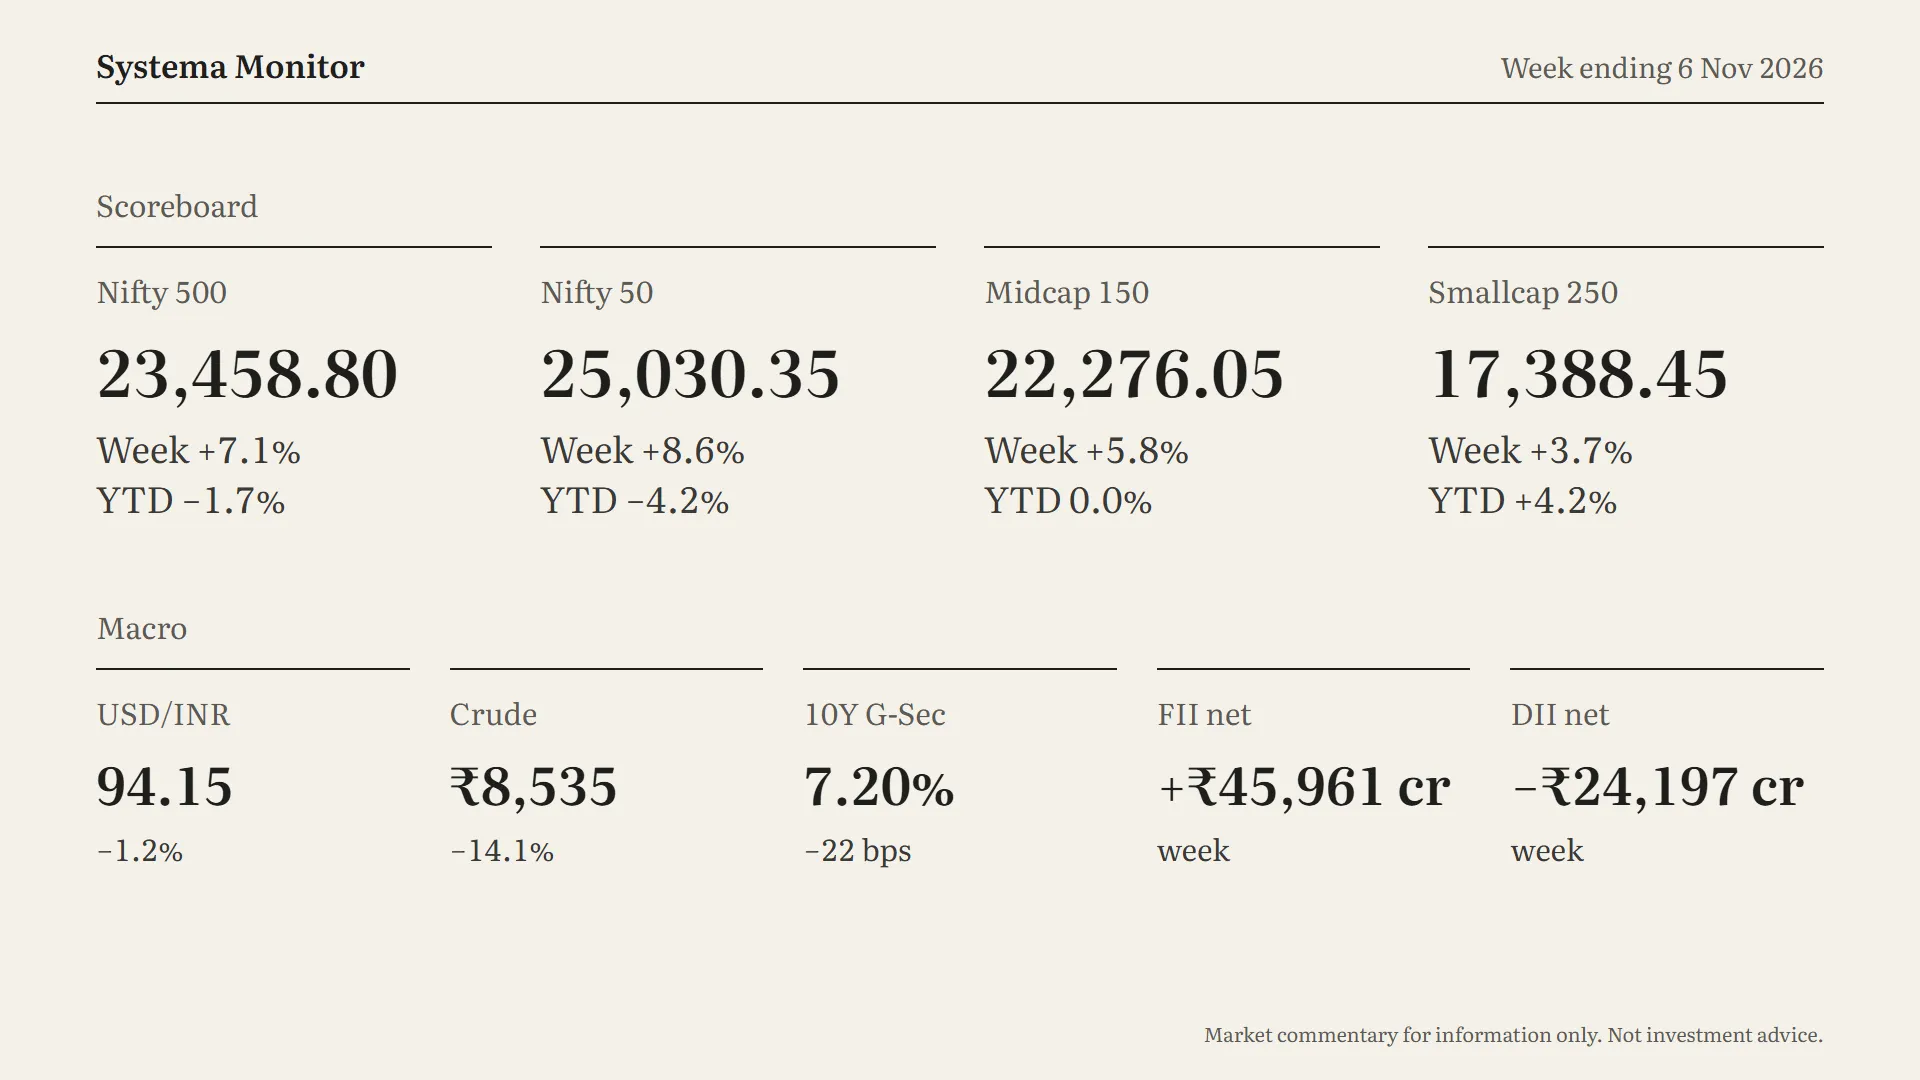
The Nifty 500 rose 7.1%, to 23,459, and the Nifty 50 rose 8.6%, to 25,030. Both are the biggest weekly gains in our records, which go back to August 2025. The Nifty 500 closed at its highest level since the end of August, and in one week it cut its loss for the year from 8.3% to 1.7%. The Nifty 50 crossed 25,000.
The size order matters here. The largest companies led and the smallest lagged: Nifty 50 +8.6%, midcaps +5.8%, smallcaps +3.7%. Midcaps are now flat for the year, and smallcaps are up 4.2%.
On to macro. Nearly everything lined up in India’s favour this week.
Crude fell 14.1%, to ₹8,535. That’s the largest weekly move in crude since it started appearing in this report, and a big relief for an oil importer.
The rupee strengthened 1.2%, to about 94.2 to the dollar.
The 10-year government bond yield fell 22 basis points, from 7.41% to 7.20%.
And flows. Foreign investors were net buyers of ₹45,961 crore, buying on every day of the week, including nearly ₹15,000 crore on Thursday alone. That’s the largest weekly figure, in either direction, since flows started appearing in this report. Domestic institutions took the other side and were net sellers of ₹24,197 crore, selling on every day of the week.
That completes a sharp turn over five weeks. At the start of October, foreign investors were selling more than ₹30,000 crore a week while domestic institutions absorbed it. Now the roles have reversed.
Breadth & Momentum
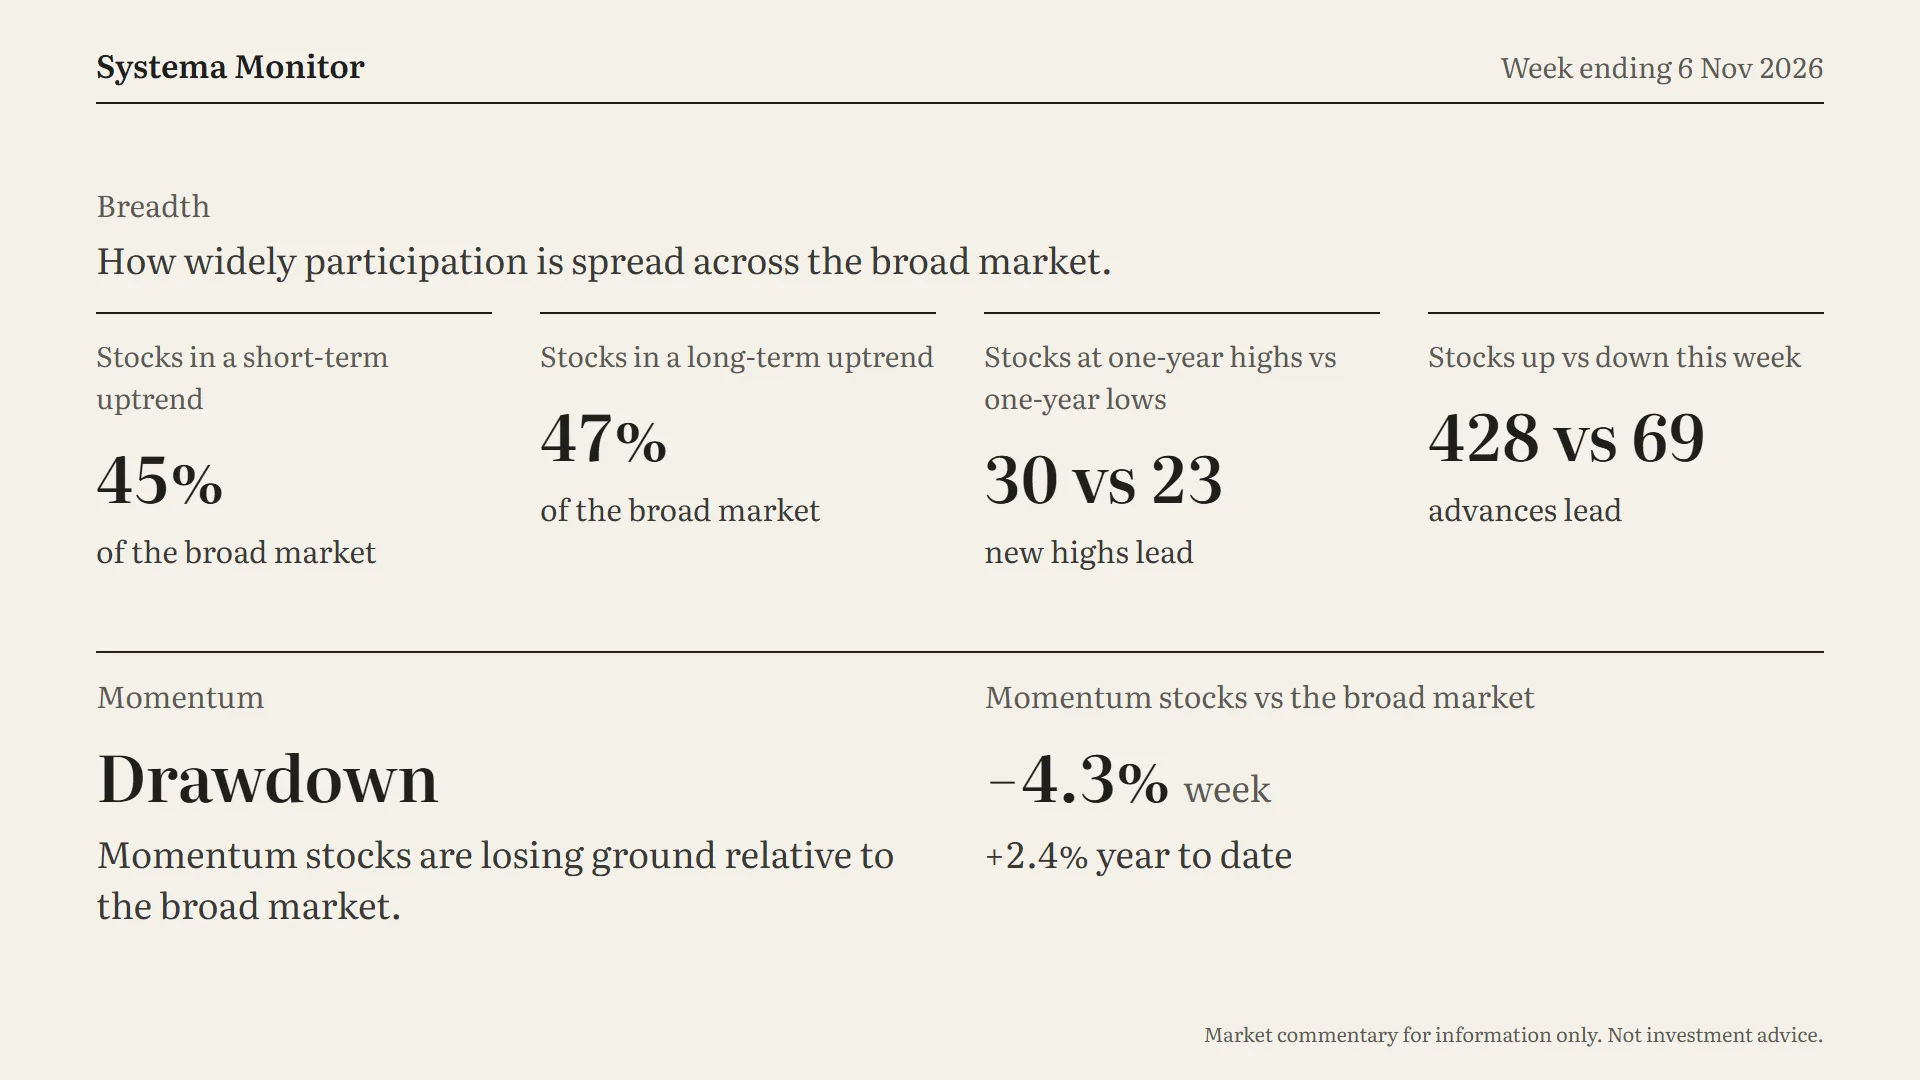
Last week we said breadth had only half-recovered. This week it caught up.
Stocks up versus down: 428 rose this week, and 69 fell. Last week it was 305 up and 191 down; two weeks ago, only 33 rose.
One-year highs versus lows: 30 new highs against 23 new lows, down from 89 new lows last week. Stocks at one-year highs outnumbered those at one-year lows for the first time since early September.
Short-term uptrend: 45% of the broad market. That’s more than double last week’s 18%.
Long-term uptrend: 47%, up from 32% last week. Nearly half the market is now in a long-term uptrend, up from a quarter two weeks ago.
Momentum is the one weak spot. Momentum stocks are back in Drawdown, meaning they’re losing ground relative to the broad market. It’s their second spell in Drawdown in three weeks. They rose this week, but they trailed the broad market by 4.3%, their worst week against it in our records. Their lead over the market for the year has shrunk to about 2.4 percentage points. In early October it was more than 8.
We’ve seen this pattern before. In mid-October, a rally led by the year’s laggards left momentum stocks behind. This week was the same thing on a much bigger scale. When the market’s laggards are bought hard, the year’s leaders don’t keep up.
Sector Leadership
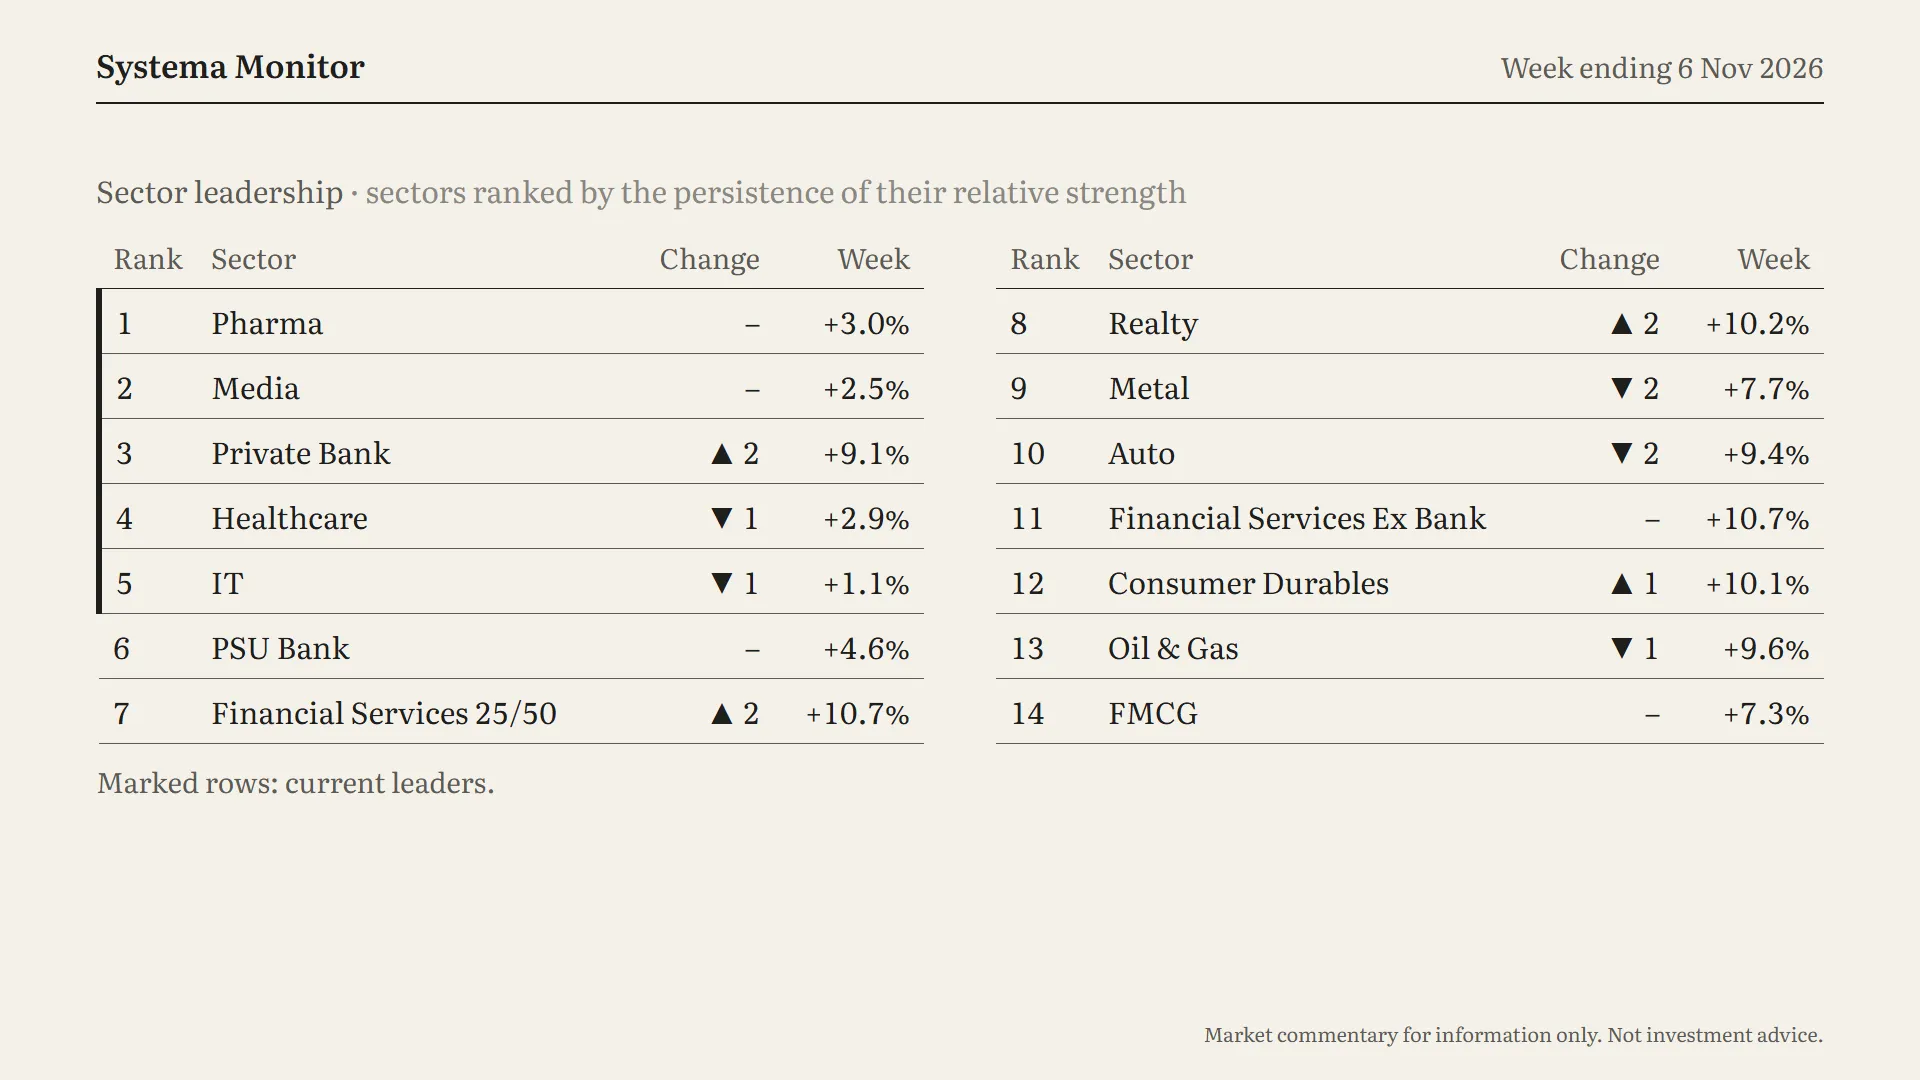
Sector leadership. As always, this table ranks sectors by how persistently they’ve been strong.
Every sector rose this week. But look at where the gains were. Financial services, realty, consumer durables, oil and gas, and autos all rose between 9% and 11%. The sectors that have led all along gained the least.
The five leaders:
- Pharma stays first, up 3.0%.
- Media holds second, up 2.5%.
- Private banks climbed two places to third, up 9.1%. They’re the only leader that kept pace with the rally.
- Healthcare slipped to fourth, up 2.9%.
- IT slipped to fifth, up 1.1%, the smallest gain of any sector.
Pharma, media, healthcare and IT were the four smallest gainers on the table. That’s why momentum lagged.
The ranking rewards persistence, so even big weeks don’t reshuffle it much. Financial services 25/50 rose 10.7% and climbed two places to seventh. Realty rose 10.2% and also climbed two, to eighth. Metal (+7.7%) and autos (+9.4%) each dropped two places, because other sectors rose more. FMCG rose 7.3% and stays fourteenth.
Week Ahead
First, a look back at two US events:
- The US Federal Reserve kept its interest rate unchanged at its 28 October meeting.
- US payrolls for October came in well ahead of forecasts. The economy added 165,000 jobs, against 65,000 expected and 60,000 the month before. The report came out on Friday evening, India time, after Indian markets had closed. This week’s moves don’t reflect it yet.
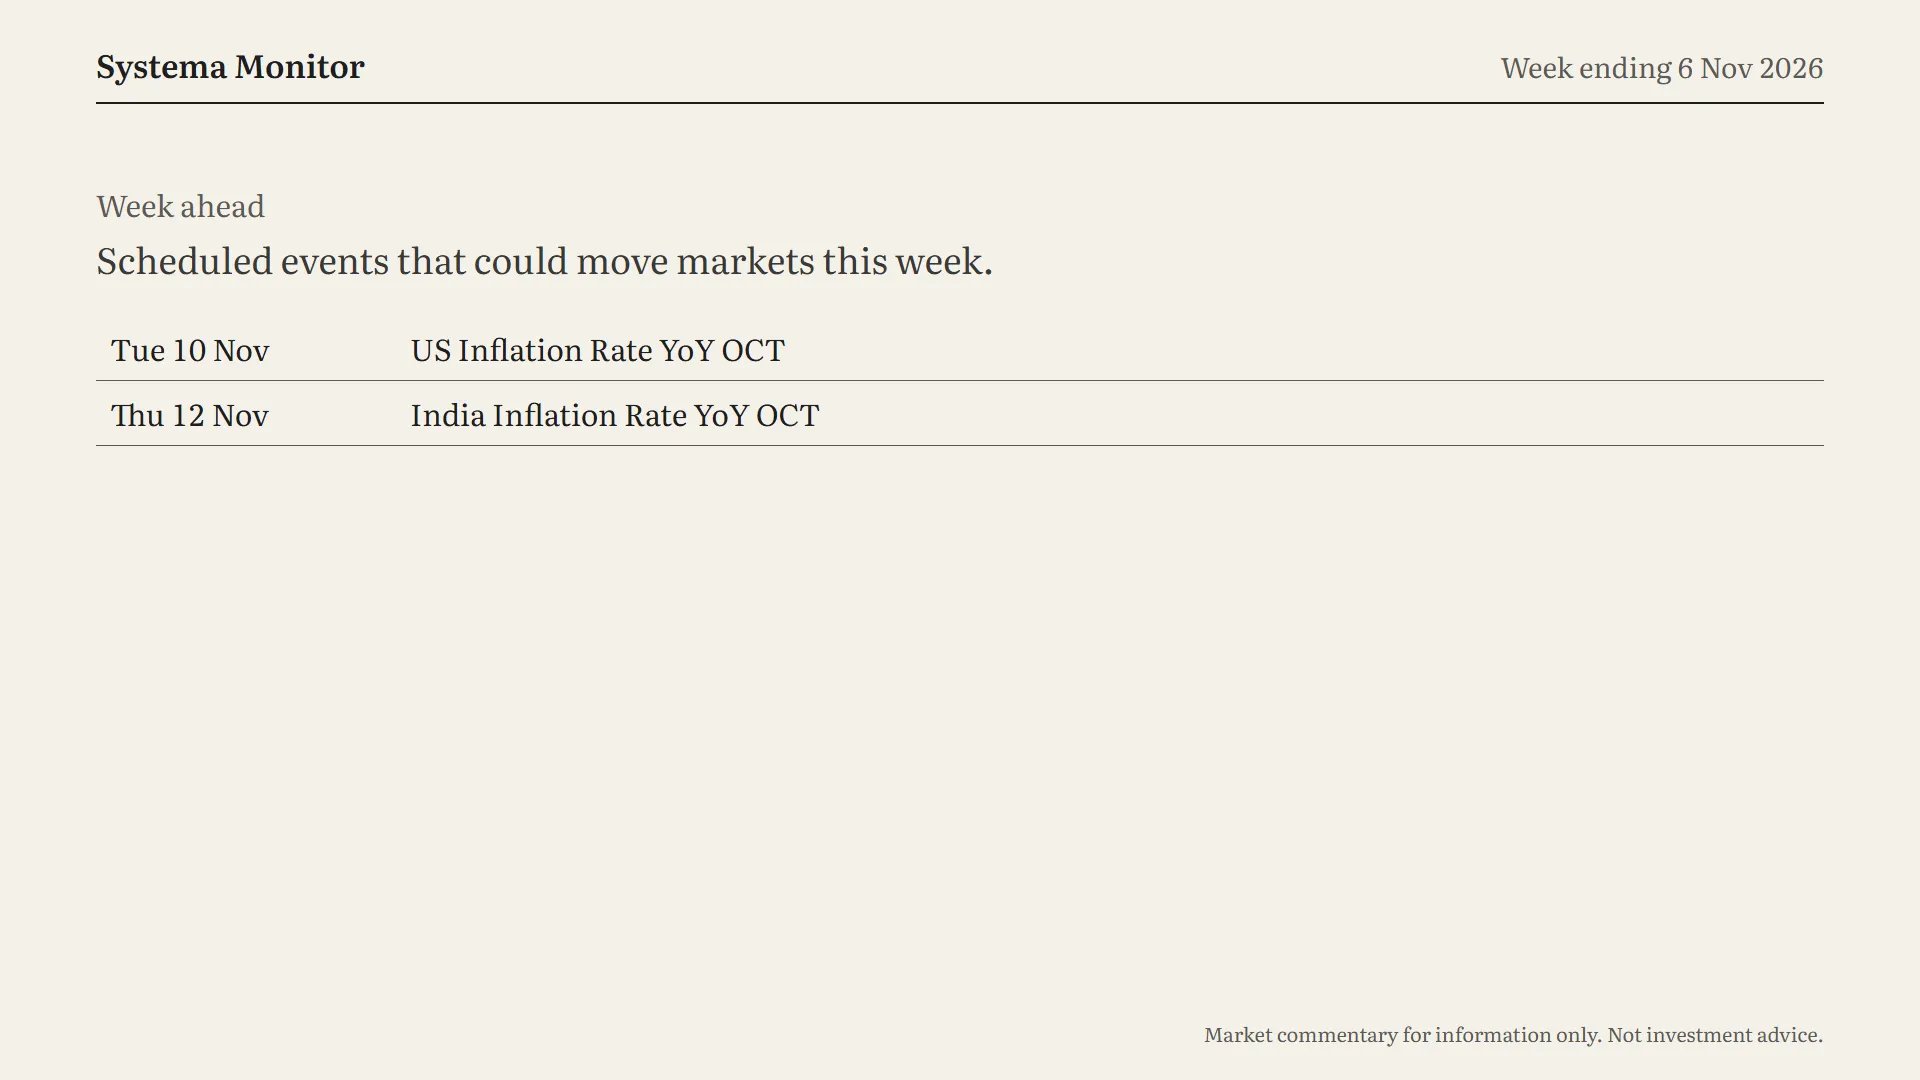
The week ahead has two inflation readings:
- Tuesday, 10 November: US consumer inflation for October.
- Thursday, 12 November: India’s consumer inflation for October.
After a week driven by falling oil, falling yields and heavy foreign buying, both numbers will test whether the moves in rates and currencies hold. Before either is out, Indian markets get their first chance on Monday to react to the strong US jobs report.
To sum up: this was the strongest week in our records. The Nifty 500 rose 7.1%, broke back above its long-term trend, and the regime moved to Fragile Uptrend. Breadth broadened sharply, new highs outnumbered new lows again, and foreign investors bought more in a week than at any point since flows started appearing in this report. Crude, the rupee and bond yields all moved India’s way. Two cautions remain. Volatility is High, so the uptrend is still fragile. And the year’s leaders sat the rally out: momentum stocks are back in Drawdown after their worst week against the market in our records. Whether this is a lasting change in leadership or another short-lived laggard rally is the question for the coming weeks.
That’s Systema Monitor for this week. Thanks for reading and see you next week.
For trade breakdowns of what I traded during the week, kindly watch this.
Referral link. *T&Cs apply. Investment in securities market are subject to market risks, read all the related documents carefully before investing. For a detailed disclaimer visit https://zerodha.com/pricing. Member ID NSE (13906), BSE (6498), MCX (46025). Brokerage will not exceed the SEBI prescribed limit.
Get new lessons by email
One email when a new article is published, free. Unsubscribe any time. We only use your email to send the newsletter; see the privacy policy.