Systema Monitor (Week 40)
Week ending 1 October: a quiet downtrend, all four main indices down over 3%, weak breadth, and Media and Private Bank join the sector leaders.
Market data in this review is as of 1 October 2026.
 Watch the video: Systema Monitor (Week 40)
Welcome to Systema Monitor, my weekly look at the Indian market. This is the report for the week ending Thursday 1 October. It was a short week: Friday was a holiday for Gandhi Jayanti.
In about five minutes, I’ll cover the market’s mood, how the main indices did, how many stocks took part, which sectors are leading, and what’s coming up next week.
This is market commentary for information only. It’s not investment advice.
Market regime
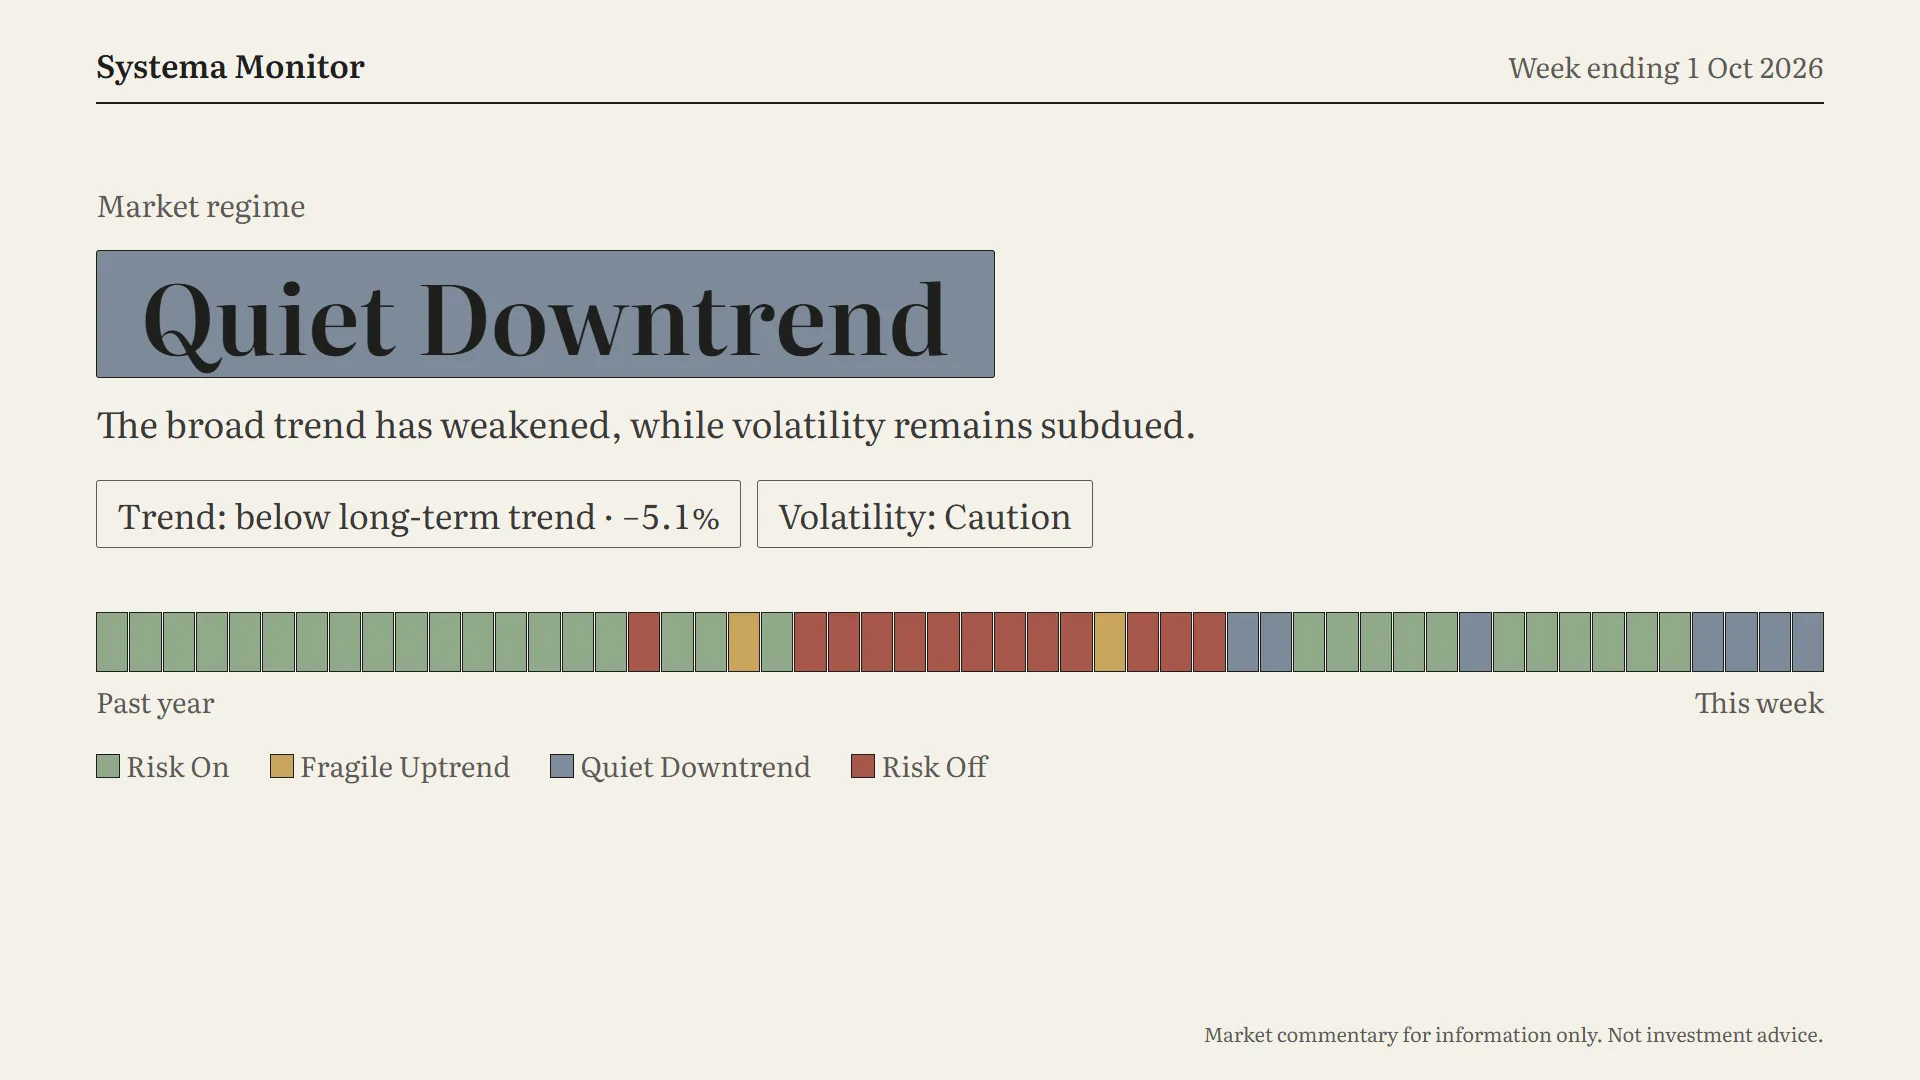
First, the market’s mood, which I call the regime. This week it’s a Quiet Downtrend: the broad trend has weakened, but volatility is still fairly calm. Markets are drifting lower rather than panicking.
Two things decide the regime. The trend: the broad market is now 5.1% below its long-term trend. And volatility: it’s at “Caution”, a middle level, not yet high.
The strip shows the past year, one box per week, with this week on the right. Green is Risk On, yellow a fragile uptrend, blue-grey a quiet downtrend, and red Risk Off. You can see the long red stretch earlier in the year, the recovery into green, and now four blue-grey weeks in a row.
Scoreboard and macro
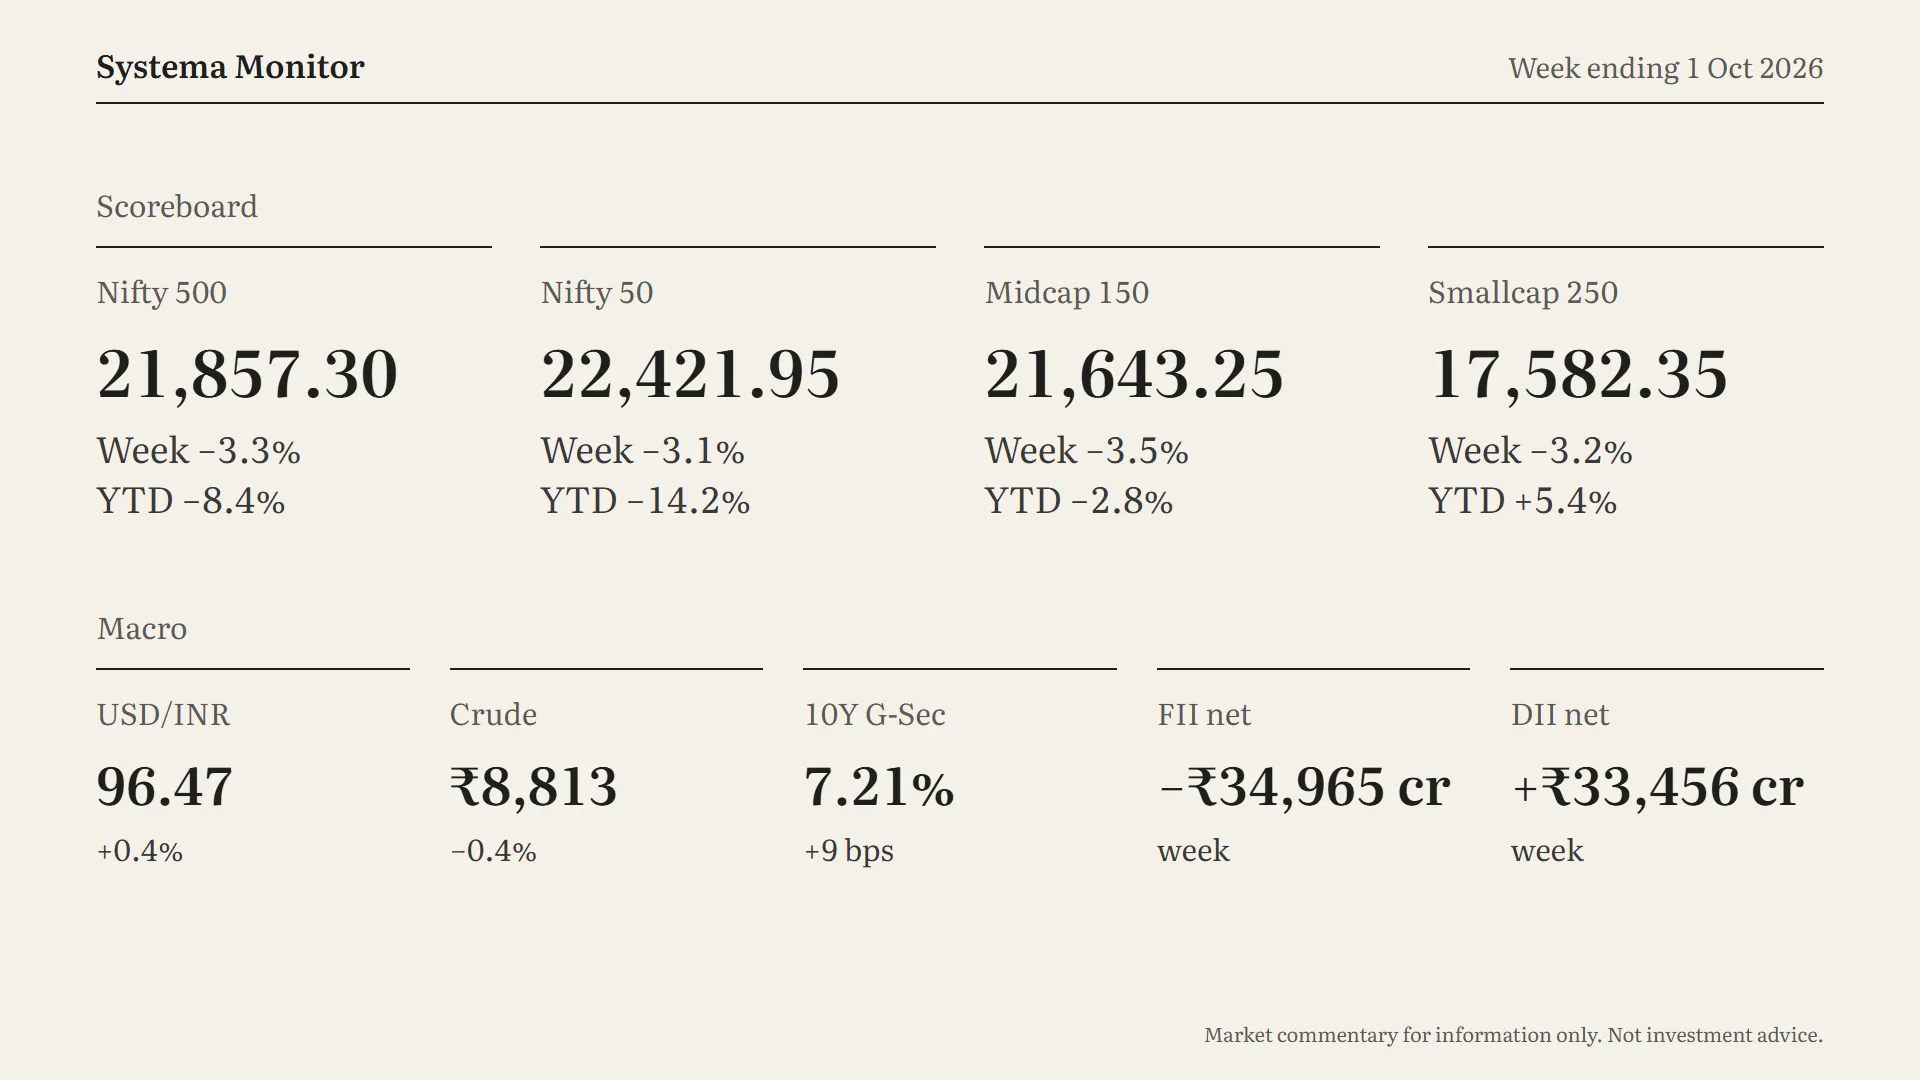
A tough week across the board. All four main indices fell between 3 and 3.5%.
The Nifty 500, the broad market, fell 3.3% and is now down 8.4% for the year. The Nifty 50, the biggest companies, fell 3.1% and is down 14.2% this year.
Mid and small companies are holding up much better over the year. The Midcap 150 fell 3.5% this week but is down only 2.8% for the year. The Smallcap 250 fell 3.2% and is still up 5.4% for the year.
Now the bigger picture. The rupee weakened slightly: the dollar now buys 96.47 rupees, up 0.4%. Crude oil eased 0.4%. The 10-year government bond yield rose to 7.21%, up 0.09 points.
The flows tell the story of the week. Foreign investors sold a net ₹34,965 crore of Indian shares in four days. Domestic institutions bought almost all of it back, a net ₹33,456 crore.
Breadth and momentum
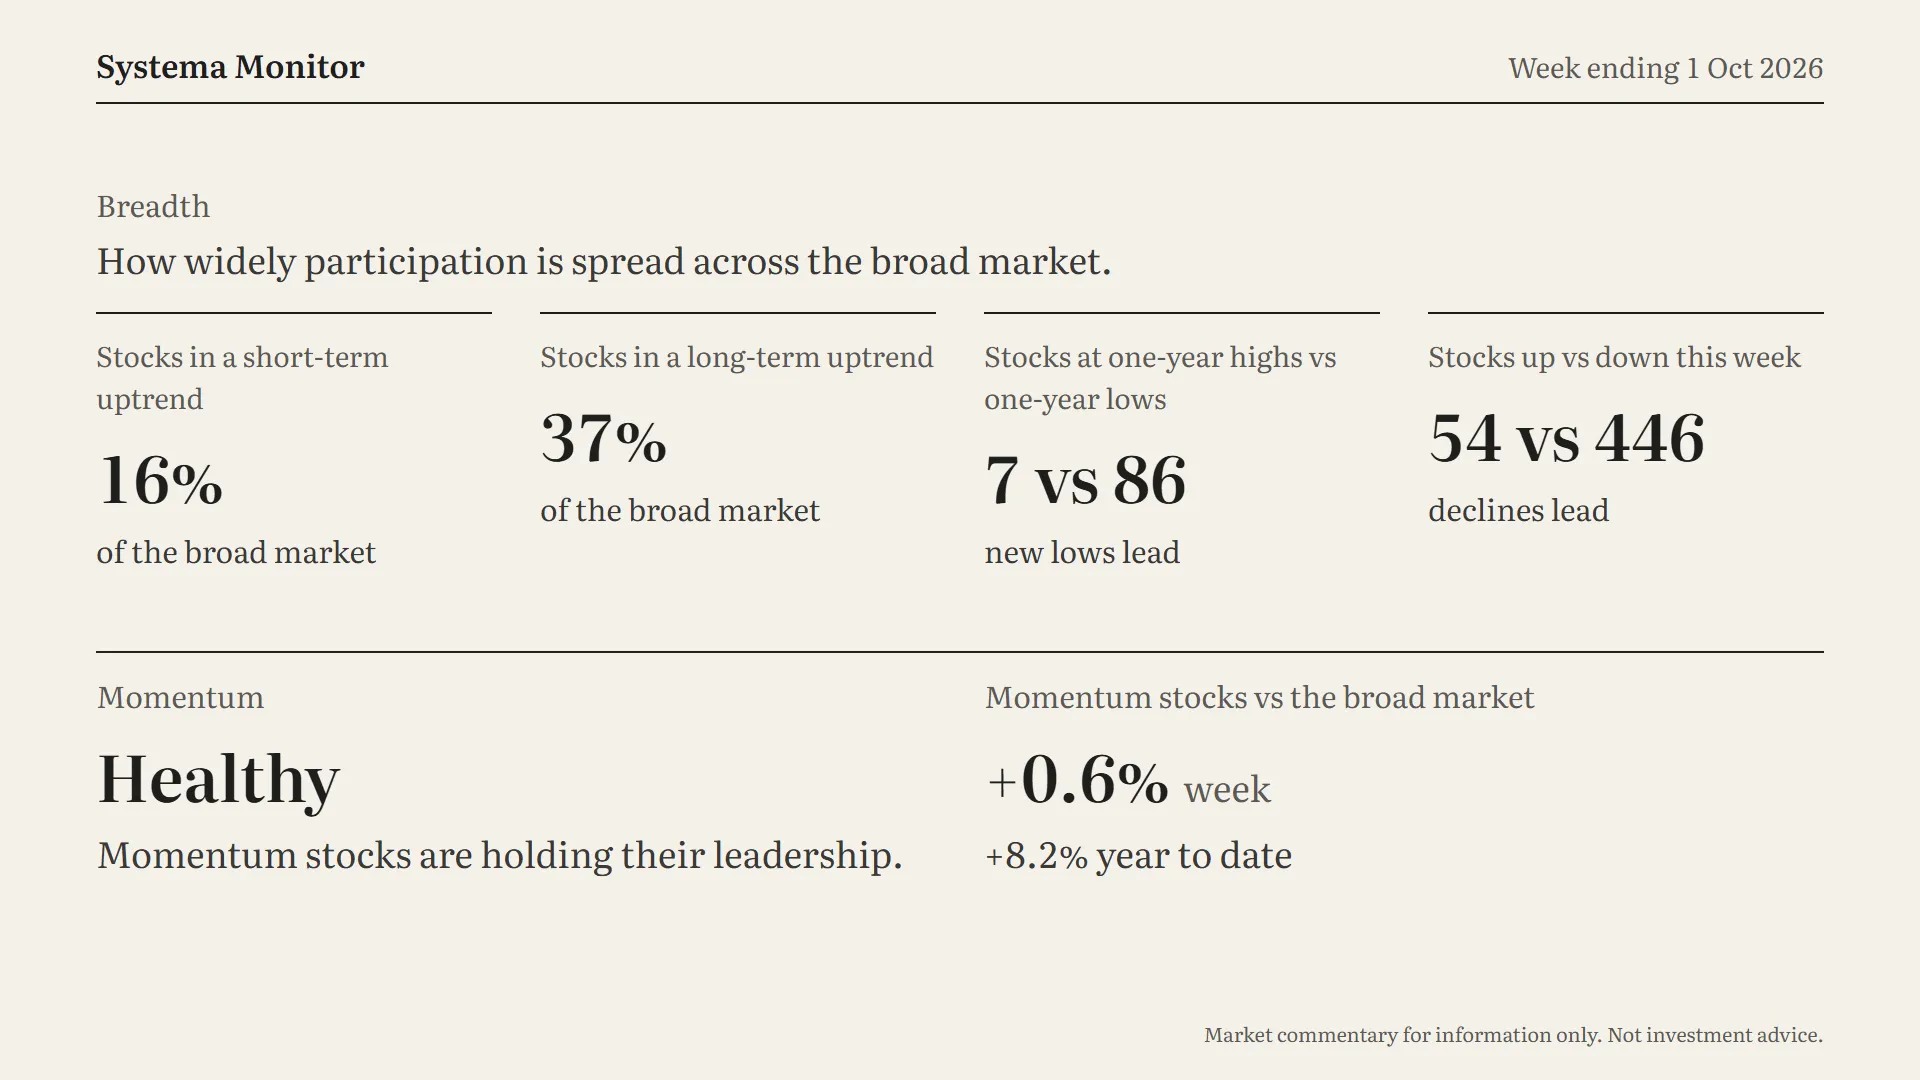
Breadth tells us how many stocks are actually taking part, not just the big index names. This week, breadth was weak.
Only 16% of stocks in the broad market are in a short-term uptrend, and 37% in a long-term one. So most stocks are not in an uptrend right now.
Just 7 stocks hit a one-year high, against 86 at a one-year low. And for the week, only 54 stocks rose while 446 fell. That’s roughly nine out of ten stocks down.
One bright spot: momentum. The strongest stocks are still holding their leadership. They did 0.6% better than the broad market this week, and they’re 8.2% ahead for the year. So even in a falling market, the leaders are falling less.
Sector leadership
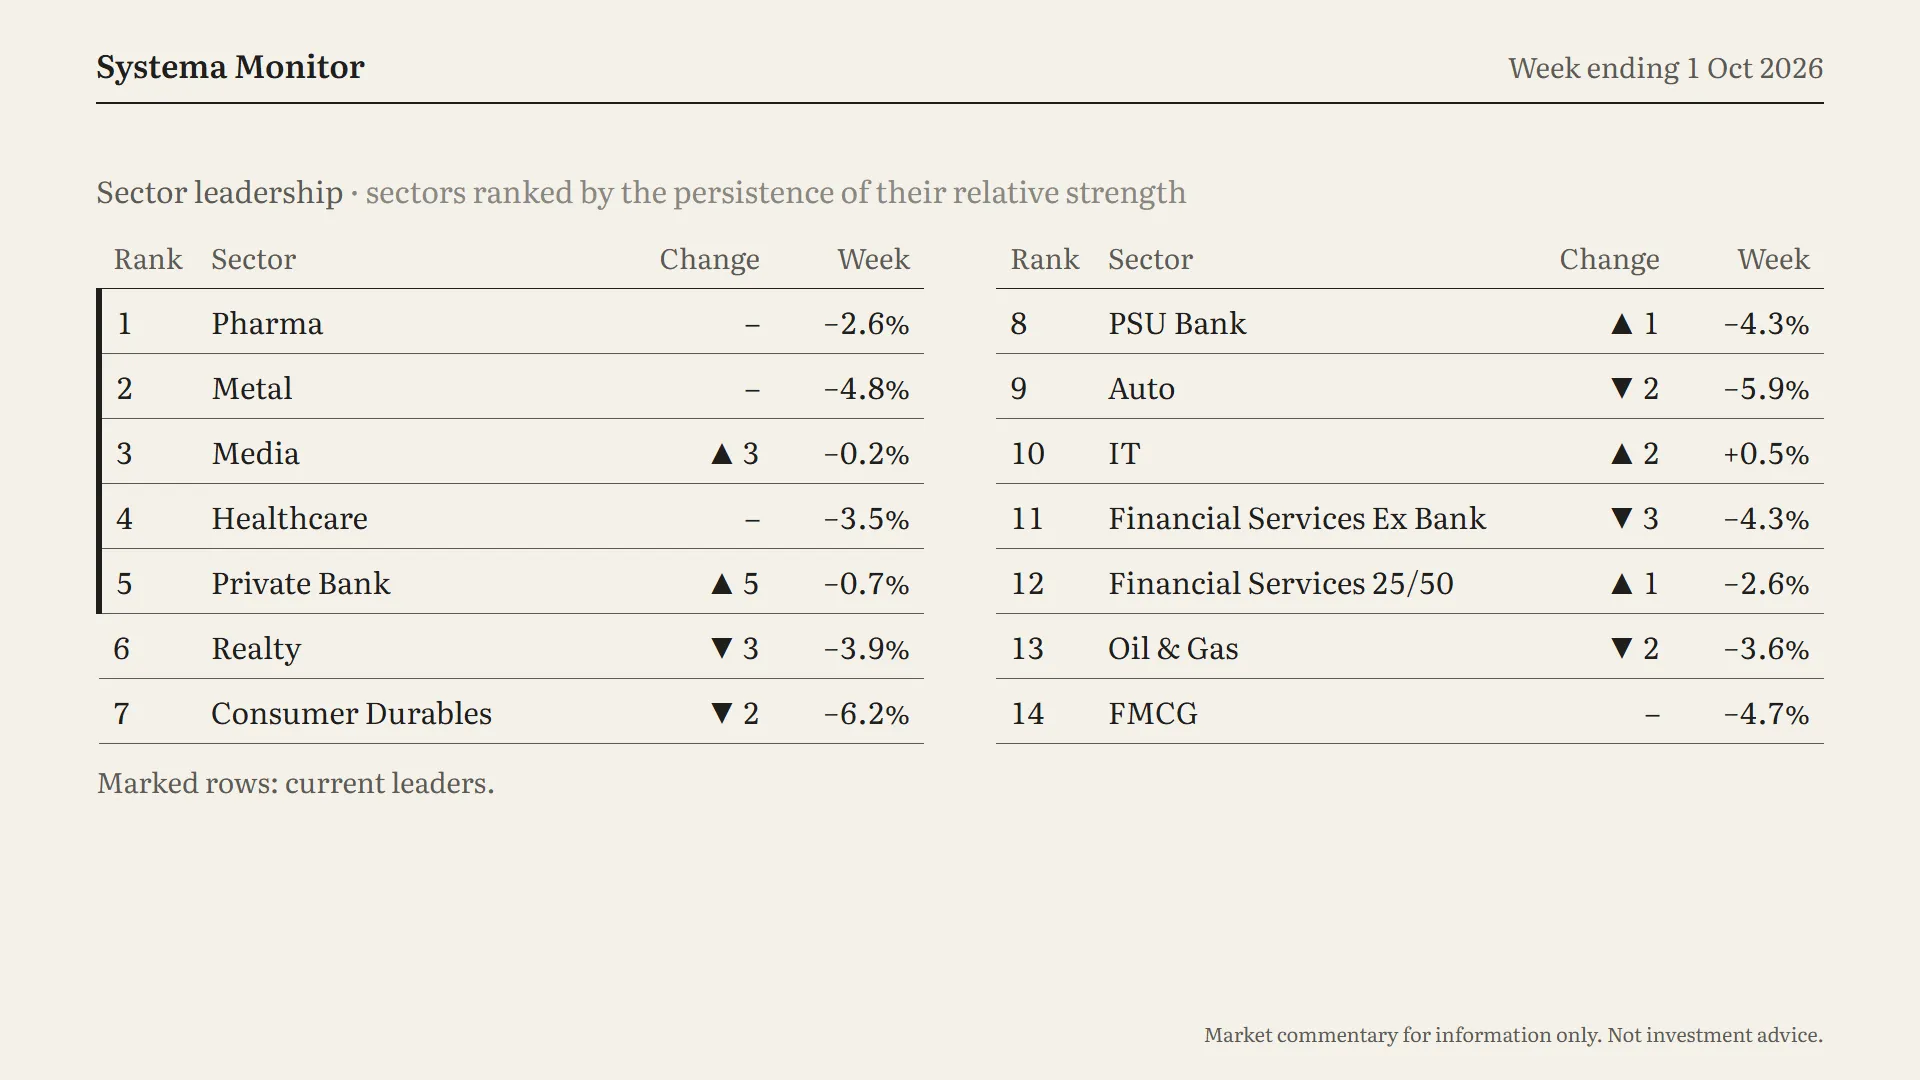
Next, sectors. These are ranked by how persistently each one has outperformed the broad market, not just by this week’s move. The top five, marked on the left, are the current leaders.
Pharma holds the top spot, then Metal. Healthcare stays in the leading group at fourth.
There are two new leaders this week. Media jumped three places to third, and Private Bank climbed five places to fifth. Both held up well this week, falling less than 1%.
Dropping out of the leaders are Realty, now sixth, and Consumer Durables, now seventh. Consumer Durables also had the worst week of any sector, down 6.2%, with Auto close behind at minus 5.9%.
And one sector actually rose this week: IT, up 0.5%, climbing two places to tenth.
Summary
To sum up: a short, weak week. The market stayed in a quiet downtrend, all the main indices fell over 3%, and nine in ten stocks closed the week lower. Foreign investors sold heavily, and domestic institutions absorbed almost all of it.
The silver linings: momentum stocks are still holding their lead, and Media and Private Bank have moved up into the leading sectors.
Next week, watch the RBI’s rate decision on Wednesday.
Referral link. *T&Cs apply. Investment in securities market are subject to market risks, read all the related documents carefully before investing. For a detailed disclaimer visit https://zerodha.com/pricing. Member ID NSE (13906), BSE (6498), MCX (46025). Brokerage will not exceed the SEBI prescribed limit.
Get new lessons by email
One email when a new article is published, free. Unsubscribe any time. We only use your email to send the newsletter; see the privacy policy.